Used Van
Finance
 HP, PCP and Finance Lease available on used vansSoft credit check, no impact on your credit score15+ specialist UK van finance lenders compared
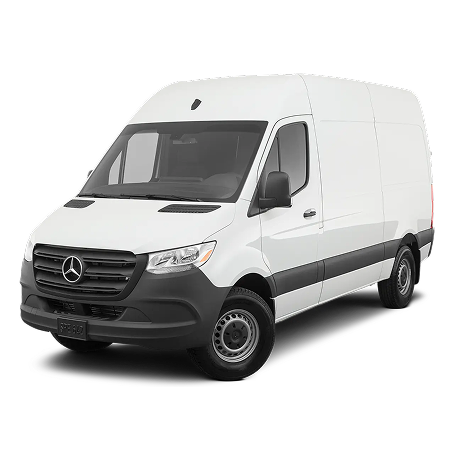
Used van finance lets you spread the cost of a second-hand van across fixed monthly payments. Borrowing £7,500 over 48 months at representative 21.9% APR works out at £228.11 per month. Rates start from 9.9% APR. Car-Finance compares used van finance deals from 15+ specialist UK lenders in one soft-search application. The initial check has no impact on your credit score.
Finance types: HP for ownership
Finance types: PCP for lower monthly payments
Finance types: Finance Lease for VAT-registered businesses
Rates from 9.9% APR, representative 21.9% APR. Final rate depends on lender, deposit and credit profile
Term: 24 to 60 months
Deposit: optional on HP and PCP. A 10% to 20% deposit lowers the monthly payment
No minimum credit score required for the initial soft check
Moneyrepublic Ltd (FRN: 967024) trading as Car-Finance acts as a credit broker, not a lender, regulated as an Appointed Representative of F&I Online Ltd (FCA No. 731217), authorised by the Financial Conduct Authority.
Last Updated: Aug 2026
How to get used van finance?
Tell us about the van
Get approved
Drive away
We Work with 15+ Trusted UK Van Finance Lenders
We work with over 15 lenders offering 100+ HP and PCP deals so that you could have the best offer.




We are credit broker, not a lender.
Used van finance calculator
Finance calculator
- 36 mo
- 42 mo
- 48 mo
- 60 mo
Your estimated examples
Representative example: Borrowing £7,500 over 48 months with a representative APR of 21.9%, monthly payment of £228.11, total cost of credit £3,449.21, total amount payable £10,949.21. Rates from 9.9% APR. We are a credit broker, not a lender.
With the help of the calculator you can roughly estimate possible loan options.
Total payable includes interest, the option-to-purchase fee, and any documentation fees. The actual rate depends on credit profile, deposit, and chosen lender.
Rates from 9.9% APR. We are a credit broker, not a lender.
What is used van finance and how does it work?
Used van finance is a credit agreement that spreads the cost of a second-hand van across fixed monthly payments. How does van finance work? Banks, brokers, and specialist lenders provide the funding under FCA regulation. A deposit reduces the loan amount and the monthly payment. The van itself acts as security on the van finance agreement.
Used van finance suits sole traders, limited companies, small businesses, and private buyers. Three product types apply to second-hand vans. Hire Purchase (HP) gives full ownership after the final payment. PCP lowers monthly payments through a balloon at the end. Finance Lease is a business-only product for VAT-registered operators. Used truck finance follows the same structure.
Car-Finance is an FCA-regulated credit broker. We compare 15+ specialist UK lenders in one soft-search application. Bad credit, CCJs, and self-employed income are accepted on the lender panel. We receive a commission from lenders when finance is arranged. This does not affect the rate you are offered. Learn more about how we make money.
How do used van finance payments work?
Used van finance monthly payments depend on six measurable factors. Each factor affects the monthly amount or the total cost of the agreement.
A used van worth £7,500 financed over 48 months at the representative 21.9% APR produces a monthly payment of £228.11. The total amount payable is £10,949.21 with no deposit, including £3,449.21 total cost of credit and a £10 option to purchase fee.
Adding a 10% deposit (£750) lowers the monthly figure to around £205.30 and reduces the total cost of credit by about £344.92. APR van finance rates depend on the lender, the van's age, and your credit profile.
Six factors affect your used van finance monthly payment:
- Deposit: optional on HP and PCP. A 10% to 20% deposit lowers monthly costs and total interest
- Loan term: 24 to 60 months. Longer terms cut the monthly figure but raise total interest
- Credit score: a higher score qualifies for a lower APR
- APR (interest rate): rates from 9.9% APR, representative 21.9% APR
- Finance type: HP, PCP and Finance Lease have different monthly cost structures
- Van price: the loan equals the van price minus any deposit
Estimate your monthly figure with the used van finance calculator above before applying.
HP vs PCP vs Finance Lease for used vans
| Feature | Hire Purchase (HP) | PCP | Finance Lease |
|---|---|---|---|
| Suitable for used vans | Widely available across age and mileage bands | Limited on older or high-mileage vans | Business only, subject to van age limits |
| Balloon payment at end | No | Yes (Guaranteed Future Value) | Optional |
| Van ownership | After final payment | Only if balloon payment is made | Never (lender retains title) |
| Mileage limits | None | Yes, excess miles charged per mile | None |
| Typical APR | 9.9% to 29.9% | 9.9% to 24.9% | 10.9% to 24.9% |
| Term | 24 to 60 months | 24 to 48 months | 24 to 60 months |
| Available to private buyers | Yes | Yes | No (business only) |
| Best used van choice | Primary route for ownership | Lower monthly route with end-of-term flexibility | VAT-registered businesses only |
Hire purchase is the most straightforward used van finance deal for ownership. No balloon payment, no mileage limit, and ownership transfers after the final payment. PCP suits buyers prioritising lower monthly payments. Finance Lease fits VAT-registered businesses only.
Benefits of getting a used van on finance
Used vans on finance spread the cost over fixed monthly payments. Benefits of used van finance include lower upfront cost on used van deals and flexible terms. Used van finance advantages cover popular UK models, including used Volkswagen finance (VW used finance) for Transporter buyers.
- Popular UK models on finance: Vauxhall Vivaro from around £10,000, Ford Transit from £12,000, Mercedes-Benz Sprinter from £15,000, Volkswagen Transporter from £18,000
- Lower cost: a 3 to 5-year-old van has absorbed the steepest depreciation
- No deposit options on HP and PCP, subject to credit profile
- Bad credit accepted: CCJs, IVAs and missed payments considered
- Soft credit check at application: no impact on your credit score
- Flexible terms from 24 to 60 months to match your cash flow
- Own the van outright on HP, with no balloon at the end
- Build credit history through on-time repayments to UK credit reference agencies
Who can apply for used van finance? What do you need to apply?
Used van finance eligibility through Car-Finance requires meeting standard criteria. The initial check uses a soft credit search with no impact on your credit score. A full credit check follows only if you proceed to a formal application.
Standard eligibility:
- Aged 18 to 79 (varies by lender)
- UK resident with a valid UK address
- Regular income: employed, self-employed, or benefits
- Valid UK driving licence
- No minimum credit score for the initial check
Used van-specific criteria:
- Sole traders and self-employed: SA302 or 2 to 3 months of business bank statements as proof of income (HMRC SA302)
- Limited companies: 12+ months of trading preferred. Director guarantee may apply
- Bad credit applicants: CCJs, IVAs and missed payments considered. A larger deposit improves approval
- Private buyers: HP and PCP available. Finance Lease is business-only
Documents to prepare:
- Valid UK driving licence
- Proof of UK address (last 3 months)
- UK bank account details
- Employed: recent payslips (last 2 to 3 months)
- Self-employed: SA302 or 2 years of accounts plus 3 months of bank statements
- Limited company directors: certificate of incorporation, director ID and address
All lenders are FCA-regulated. An affordability assessment runs before approval.
Why choose us?
Check your eligibility online

Soft credit check, no impact on your score. Apply in minutes, no paperwork, decision same day.
Buy a van from any dealer

Collect from any FCA-registered dealer or arrange delivery.
Van finance quality assured

Every van HPI checked: outstanding finance, written-off history, mileage and MOT history.
15+ UK lenders compared

We find your best rate automatically in one search.
FCA authorised

Free service, no hidden fees, no commission added to your rate.
Used van specialists

HP, PCP & Finance Lease compared in one soft-check search. Sole traders, Ltd companies and private buyers all accepted.
Frequently asked questions about used van finance

Can I get used van finance with bad credit?
Yes. Specialist lenders on the Car-Finance panel accept used van finance bad credit applications. CCJs, IVAs and missed payments are considered. The initial soft search has no impact on your credit score. A larger deposit improves approval odds. All lenders are FCA-regulated and run an affordability assessment before approval.
Does applying affect my credit score?
No. The initial eligibility check on Car-Finance uses a soft credit search. A soft search leaves no footprint on your credit file. A hard credit check is only carried out if you accept an offer and proceed to a formal application. The lender runs this check with your consent.
How quickly can I get approved?
Most applicants receive a decision on the same day. The soft-search form takes minutes to complete. Final paperwork and van collection typically take 2 to 5 working days, depending on the lender and dealer. Providing income and ID documents upfront speeds the process.
What types of used van finance are available?
Five products apply to used vans on the Car-Finance panel. They are Hire Purchase (HP), Personal Contract Purchase (PCP), Conditional Sale (CS), Business Contract Hire (BCH), and Finance Lease. HP is the most widely available on older and high-mileage vans. Finance Lease and BCH are business-only and suit VAT-registered operators.
What deposit is typically required for used van finance?
Most lenders do not require a minimum deposit on HP or PCP agreements. A deposit of 10% to 20% of the van's price lowers your monthly payment. It also improves your approval odds, particularly with adverse credit. No deposit van finance and used van leasing no deposit options are available subject to affordability.
What happens at the end of a used van PCP agreement?
Three options apply at the end of a PCP agreement. You can return the van and walk away. You can pay the Guaranteed Future Value (balloon payment) to take ownership. Or you can part-exchange the van and use any equity as a deposit on your next finance agreement.
Can I get used van finance as a self-employed sole trader?
Yes. Self-employed sole traders qualify for used van finance through Car-Finance. Lenders accept an SA302 tax calculation from HMRC, 2 years of accounts, or 3 months of business bank statements as proof of income. Visit van finance for self-employed for documentation guidance.
What is the difference between HP and Conditional Sale on a used van?
HP and Conditional Sale are structurally identical agreements. Both split the van's full price into fixed monthly payments. HP transfers ownership after the final payment plus an option-to-purchase fee of around £100 to £200. Conditional Sale transfers ownership automatically on the final payment, with no extra fee.
Are there age and mileage restrictions on used van finance?
Yes. Most lenders cap the van's age at 10 to 12 years at the end of the agreement. Mileage is typically capped at 120,000 to 150,000 miles. Specialist providers on the Car-Finance panel may accept older or higher-mileage vans, subject to affordability and security checks.
What is Finance Lease and who is it for?
Finance Lease is a business-only used van finance product. The lender retains legal ownership throughout the term. Monthly payments cover use of the van, not purchase. VAT-registered businesses can reclaim VAT on the finance payments. Finance Lease is not available to private individuals.
How does my credit score affect the rate I am offered?
A higher credit score qualifies for a lower APR. Each lender uses its own scoring model. A decline by one lender does not mean a decline by all. True 0% finance on used vans is rare and typically limited to new-van manufacturer schemes. Car-Finance compares 15+ UK lenders, with rates from 9.9% APR.
Compare used van finance with Car-Finance today
Finance Lease is a business-only used van finance product. The lender retains legal ownership throughout the term. Monthly payments cover use of the van, not purchase. VAT-registered businesses can reclaim VAT on the finance payments. Finance Lease is not available to private individuals.
Apply for used van finance deals today. Free service and no credit impact.
Compare used van finance from 15+ specialist UK lenders in one free soft-search application. HP, PCP and Finance Lease available. The initial check has no impact on your credit score.